Water damage? Don't wait.
Call (855) 529-0071 — 24/7 emergency help across 17 states. Free inspection, written scope.
Blog
Home » Blog » Storm Damage Restoration: From Tarp to Rebuild Guide
Storm damage restoration is what happens after the wind dies down, the rain stops, and you're left staring at a torn roof, a flooded living room, or a tree where your garage used to be. Hurricanes in Florida and the Gulf Coast, tornadoes across the Midwest, hailstorms in Texas, and nor'easters in New England each leave a different fingerprint of destruction — but the recovery process follows the same proven sequence: secure the home, remove the water, dry the structure, remove what's ruined, and rebuild.
This guide walks through that sequence in the order professionals actually work it, with realistic timelines, cost ranges, and the mistakes that turn a two-week recovery into a two-month one.
The first day is about stopping the damage from getting worse. Insurance adjusters call this "mitigation," and most policies require you to take reasonable steps to protect the property — failing to tarp a hole in the roof, for example, can jeopardize coverage for the water damage that follows.
If shingles, flashing, or decking are torn away, rain will keep pouring into the attic and living spaces until the hole is covered. Heavy-duty tarps (at least 6 mil, secured with furring strips nailed to the roof — never just bricks or rope) can hold through weeks of weather if installed properly. For broken windows, board them with 5/8-inch plywood screwed into the framing, not just taped. Temporary fixes don't need to be pretty; they need to hold.
Fallen trees on structures, downed power lines, dangling gutters, and unstable chimneys are life-safety issues. Stay clear of downed lines — call your utility and let crews handle them. For trees pressing on the house, a tree service with a crane can lift them off without dragging the trunk across the roof, which is what causes most of the secondary damage in amateur removals.
If water got into electrical panels, outlets, or the HVAC, kill the power to affected areas. If you smell gas, leave and call the gas company from outside. A flooded water heater or furnace should be evaluated before it's ever switched back on — energizing wet equipment is how post-storm house fires start.
Photograph and video every room, the roof, the exterior, and the damage from multiple angles before any cleanup begins. Capture the high-water marks, the torn materials, and the source of damage if it's visible. Your adjuster will build the claim on this evidence, and once cleanup starts, the "before" picture is gone forever.
Storms don't just break things — they soak them. Rain driven through a breached roof can saturate attic insulation, ceiling drywall, wall cavities, and flooring on multiple levels. The water phase of storm damage restoration runs on the same clock as any flood: 24 to 48 hours before mold gains a foothold.
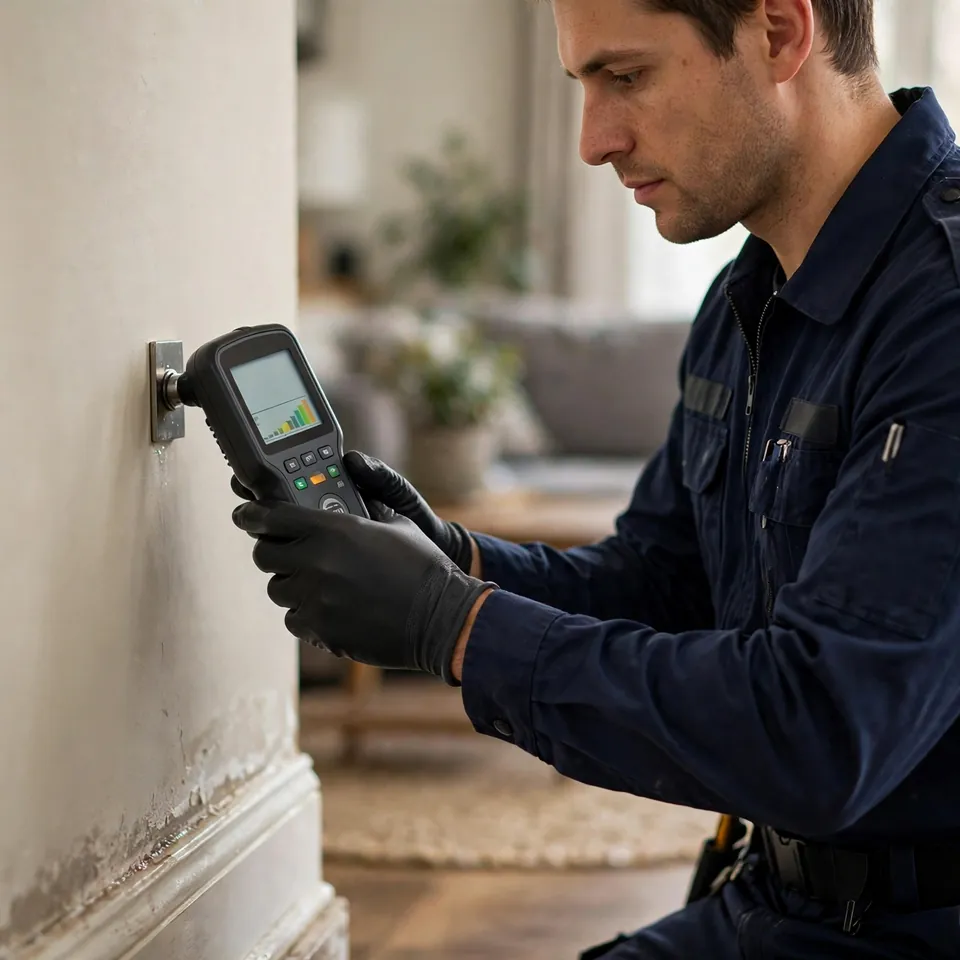
Professional crews work top-down: extract standing water first, then attack the hidden moisture. Attic insulation that's soaked is usually removed rather than dried — wet insulation loses its R-value and becomes a mold reservoir. Ceiling drywall that sags or shows staining typically comes down; it's cheap to replace and dangerous to trust. Wall cavities get moisture-meter readings, and sections above the waterline that wicked moisture upward are cut out so the studs behind them can dry.
Commercial dehumidifiers and air movers run continuously, usually 3 to 5 days, with daily moisture readings to confirm the structure is actually drying — not just feeling dry on the surface. This measurement-driven drying is what separates a real restoration from a "we ran some fans" job. A proper dry-out is also the prerequisite for everything that follows: you cannot rebuild on wet framing without setting the stage for a mold problem later.
While drying runs, the assessment and insurance process moves in parallel. A thorough assessment covers:
Get the adjuster's inspection scheduled quickly, but don't wait for the check to start mitigation — your policy requires you to protect the property now. Keep every receipt for emergency repairs, tarps, hotels, and meals; "additional living expenses" coverage reimburses these. If the adjuster's number looks low, you can get an independent contractor estimate and negotiate — the first offer is frequently not the final one.
One critical note for hurricane and tornado zones: check whether your policy has a separate windstorm or hurricane deductible, which is often a percentage of the home's coverage amount (1–5%) rather than a flat amount. On a $300,000 policy, a 2% hurricane deductible is $6,000 — a very different number than the $1,000 standard deductible most homeowners expect.
Once dry, everything that's ruined comes out. This is demolition with a purpose: remove only what can't be saved, and preserve everything that can.
Debris removal for a major storm event isn't a few trash bags — it's dumpsters, and in widespread disaster zones, dumpster and hauling capacity gets scarce. Crews that pre-schedule hauling avoid the week-long waits that stall projects after regional storms.
The rebuild phase is where storm damage restoration becomes construction. The order matters:
Timeline reality check: a single-room storm repair can finish in 3–4 weeks. A whole-house hurricane restoration with roof replacement and multi-room rebuilds typically runs 8–16 weeks, longer if contractor capacity is strained across a disaster region. After major hurricanes, reputable crews book out for months — which is one more reason to start the process the day the storm passes.
No two storms produce the same bill, but these 2026 US ranges cover the most common line items:
| Repair item | Typical cost range |
|---|---|
| Emergency tarping / board-up | $500 – $2,000 |
| Tree removal from structure | $1,000 – $5,000 |
| Roof repair (partial) | $1,500 – $6,000 |
| Full roof replacement | $8,000 – $25,000+ |
| Water extraction + drying | $2,000 – $6,000 |
| Mold remediation (per area) | $1,500 – $6,000 |
| Drywall replacement (per room) | $1,000 – $3,000 |
| Flooring replacement (per room) | $1,500 – $5,000 |
| Siding repair/replacement | $2,000 – $12,000 |
| Full interior rebuild (major event) | $20,000 – $75,000+ |
The multiplier effect is real: a $1,200 tarp job done on day one can prevent $15,000 in additional water damage over the following week. Speed is the cheapest material in restoration.
Your restoration plan should reflect your region's signature peril — hail country needs a roofer who understands impact damage; hurricane country needs crews experienced with surge contamination and wind-driven rain intrusion.
Good to know
A minor repair — tarping, drying one room, patching a roof section — can wrap in 1 to 3 weeks. A major event with roof replacement and multi-room interior rebuild typically takes 8 to 16 weeks. After regional disasters, contractor backlogs can extend timelines further, which is why starting mitigation immediately matters.
Standard policies cover wind, hail, and falling-object damage. Flood damage — including storm surge — requires separate flood insurance. Water damage from a storm-created opening (rain entering through a wind-torn roof) is generally covered as wind damage; water that seeps in from the ground up usually isn't. Check your hurricane/windstorm deductible, which may be a percentage of the coverage amount.
Yes — two or three written estimates from established local companies. After a storm, be wary of anyone who pressures you to sign immediately or asks for a large cash deposit. A legitimate contractor provides a detailed written scope, a start date, and references you can actually call.
Often yes, if the damage is contained to part of the house and utilities are safe. Whole-house roof replacements and major interior rebuilds may make temporary relocation more practical — and your policy's additional living expenses coverage exists for exactly this. Crews can usually phase work to keep part of the home livable.
Mitigation is the emergency phase: tarping, board-up, water extraction, and drying — everything that stops the damage from growing. Restoration is the rebuild phase: repairing the roof, replacing drywall and flooring, and returning the home to its pre-storm condition. Both matter, and mitigation must come first.
The highest-ROI upgrades are impact-resistant roofing, a sealed roof deck, reinforced garage doors (a common failure point in hurricanes), storm shutters or impact windows, and proper drainage away from the foundation. Many insurers discount premiums for documented wind-mitigation features — ask your agent which upgrades qualify. Storms don't wait, and neither should your recovery. Water Damage Cleanup Now connects you with local [storm damage repair](/services/storm-damage-repair/) professionals who handle everything from emergency tarping to full rebuilds. Call (855) 529-0071 any time — the sooner mitigation starts, the smaller the final bill.
Call (855) 529-0071 — 24/7 emergency help across 17 states. Free inspection, written scope.